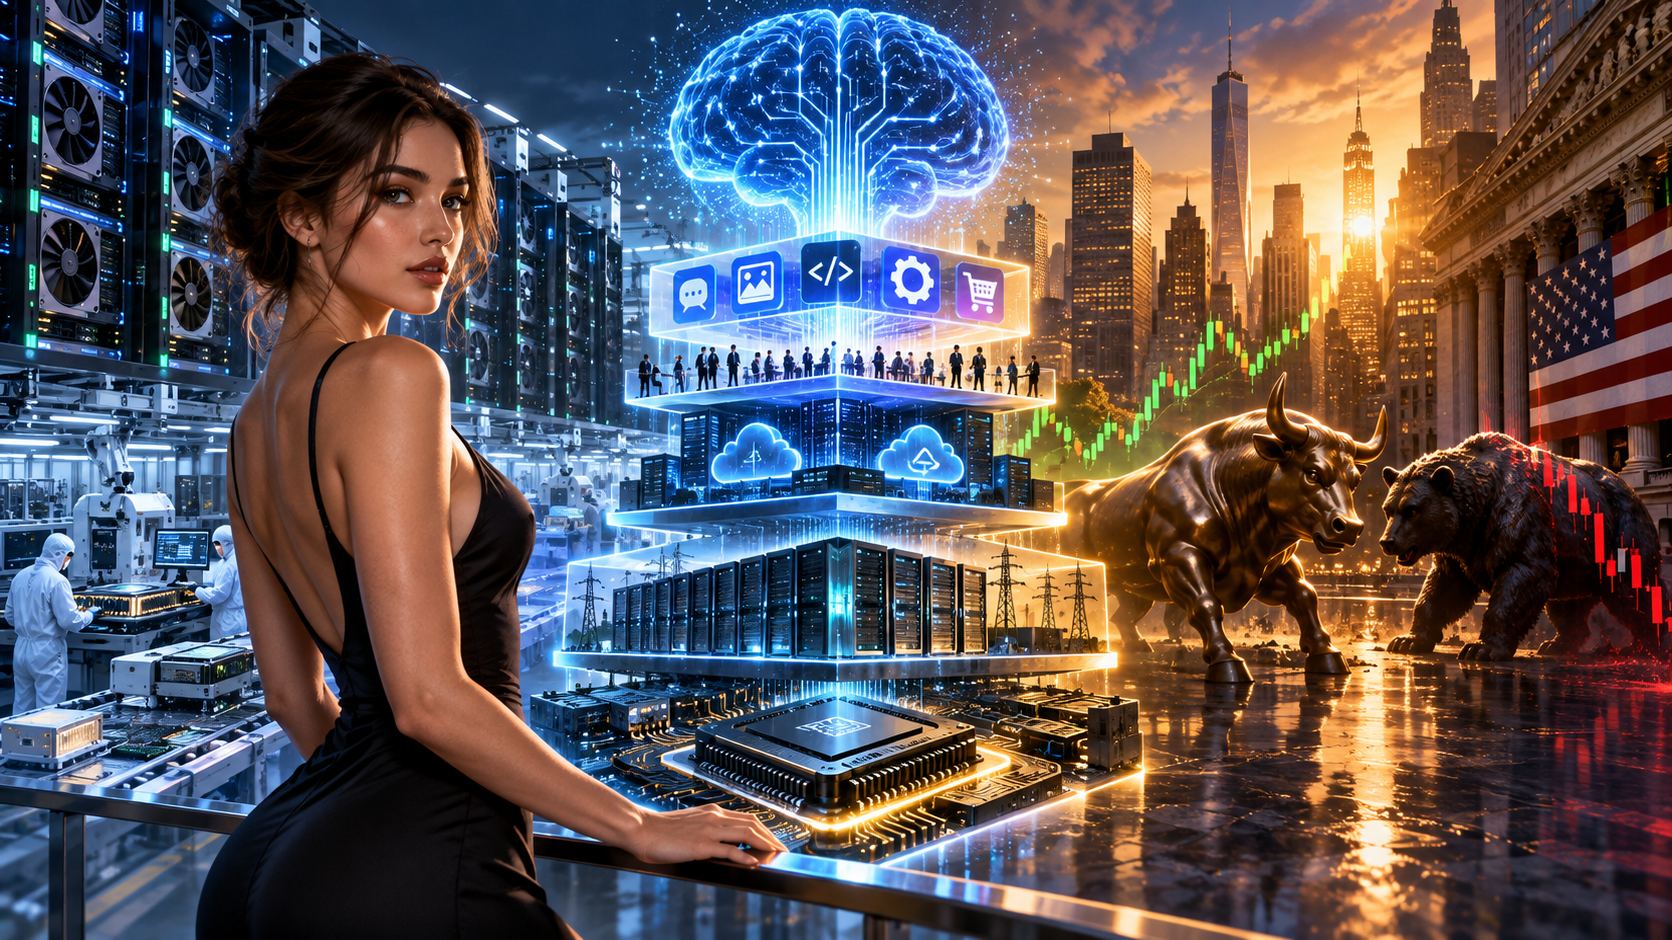
For most of the generative AI boom, Wall Street treated artificial intelligence less like a technology stack than a single enormous trade.
Nvidia sold the GPUs. Hyperscalers built the data centers. Memory manufacturers supplied the components. Cloud companies rented the compute. Software developers added AI features. If a company could attach itself convincingly enough to the theme, investors were often willing to look further down the road for the financial payoff.
This week offered a glimpse of a more complicated market.
On Monday, September 14, semiconductor stocks were hammered after prominent AI executives called for slowing the development of increasingly capable systems over safety concerns. Nvidia fell 3.4%, Broadcom lost nearly 5%, AMD and Micron dropped more than 4%, and the Philadelphia Semiconductor Index sank 5.9%. Software stocks, by contrast, rallied as investors reconsidered what slower frontier-model development might mean for companies further up the economic stack.
Meta gained during the selloff. Datadog rose 4%. The pattern was hardly universal, and subsequent trading remained messy. Akamai, another useful company for examining this divide, actually slipped 1.1% on Monday before edging higher the following session.
One or two trading days do not establish a new regime. But they do expose a question that has been building underneath the AI trade for months: what if investors stop valuing every part of the AI economy as though it benefits equally from faster spending?
With the US 10-year Treasury yield hovering around 5% and AI capital expenditures reaching extraordinary levels, that question suddenly has much more financial weight.
Table of Contents
- The AI trade is really an economic stack
- A 5% Treasury yield changes the calculation
- Meta shows why the split gets complicated
- Datadog represents a different AI equation
- Akamai sits awkwardly between both worlds
- Wall Street may be moving from construction to monetization
- What would confirm that the AI trade is really splitting?
- The AI trade: key questions
The AI trade is really an economic stack
Artificial intelligence may look like software when somebody opens a chatbot, generates an image or asks an agent to write code. Economically, the process starts much further down.
At the bottom are semiconductors and components: GPUs, CPUs, memory, networking silicon and the equipment required to manufacture them.
Above that sits physical infrastructure: servers, cooling systems, networking equipment, power generation, transmission capacity and enormous data centers.
Cloud providers then turn that infrastructure into rentable computing capacity. Model developers use the compute to train and operate increasingly sophisticated AI systems. Finally, software companies and other businesses build products and services on top of those models.
The chain can therefore be simplified as:
chips → data centers → cloud and models → software and applications → customers.
During the first phase of the generative AI boom, the economic signal traveled largely in the opposite direction. Explosive demand for AI applications created an expectation of enormous future compute requirements, which justified more data centers, which required more servers, which required more accelerators and memory.
That made infrastructure one of the cleanest ways to express enthusiasm about AI.
Nvidia did not need to know exactly which chatbot, coding agent or enterprise application would eventually dominate. It benefited from the competition to build them.
But that logic has a hidden assumption: the infrastructure race needs to remain extremely fast.
Monday’s selloff showed what happens when investors briefly question that assumption. If frontier-model development slows, even temporarily, the immediate economic risk is concentrated among businesses whose revenue depends on customers continuing to order enormous quantities of physical capacity.
Software can face a different equation. Existing compute does not disappear because the next frontier model arrives six months later. Companies can continue deploying applications on infrastructure that has already been built.
That distinction is becoming harder to ignore.
A 5% Treasury yield changes the calculation
The timing matters because AI infrastructure is colliding with a very different interest-rate environment.
The benchmark US 10-year Treasury yield moved around the 5% threshold this week, reaching levels not seen since 2007 as markets wrestled with inflation, oil prices, government borrowing and Federal Reserve policy.
For an industry attempting one of the largest infrastructure buildouts in technology history, expensive capital is not background noise.
Building AI capacity requires spending money today for economic returns that may arrive years later. Data centers need land, power equipment, cooling, networking and servers filled with rapidly depreciating hardware. New power generation and transmission can stretch the investment horizon even further.
Higher long-term rates raise financing costs while also increasing the return investors can obtain from comparatively low-risk government debt. Both effects make distant corporate cash flows less attractive.
This is where the distinction between AI infrastructure and AI applications becomes financially meaningful.
An infrastructure company may need to spend billions before the capacity generates revenue. A software company can potentially add an AI service to an existing product, sell it through an existing distribution network and collect recurring revenue without owning the entire physical stack underneath it.
That does not automatically make software economically superior. Software companies still pay cloud bills, spend heavily on engineering and face intense competition. AI inference itself can become expensive at scale.
But the amount of capital required to generate the next dollar of revenue can differ enormously across the AI stack.
At 2% long-term yields, Wall Street can be unusually patient with that distinction.
Around 5%, patience becomes more expensive.
Meta shows why the split gets complicated
Meta is an especially interesting case because it belongs on both sides.
The company is one of the world’s largest AI infrastructure spenders. In its second-quarter filing, Meta projected $130 billion to $145 billion of capital expenditures for 2026, including principal payments on finance leases. Second-quarter capex alone reached $31.08 billion.
That spending is enormous enough to make Meta part of the infrastructure story whether investors like it or not.
Yet Meta also owns something Nvidia does not: a gigantic existing monetization machine.
Facebook, Instagram, WhatsApp and the company’s advertising systems give Meta direct channels through which improvements in AI can potentially translate into engagement, ad performance and revenue. In the second quarter, Meta generated $60.8 billion in revenue, up 28% year over year. Ad impressions increased 14%, while average price per ad rose 12%.
This makes Meta’s position unusual. It is paying the infrastructure bill while simultaneously trying to prove what the infrastructure can earn.
The company’s shares rising during Monday’s semiconductor rout can therefore support more than one interpretation. Investors may have viewed a possible slowdown in the frontier race as reducing pressure on future capital expenditures. They may also have decided that Meta’s existing products give it more ways to monetize AI investment than companies selling capacity into the buildout.
Neither interpretation means Meta suddenly becomes an asset-light AI company. Its 2026 spending plans make the opposite obvious.
Meta is useful precisely because it breaks the neat infrastructure-versus-applications binary.
The AI economy is a stack, but some of its largest companies occupy several layers at once.
Datadog represents a different AI equation
Datadog offers a cleaner example of what investors may eventually demand from the application and software side.
The company does not need to manufacture GPUs or construct hyperscale data centers to benefit from increasingly complex AI systems. Its business is built around observability and security: helping customers understand what their software and infrastructure are doing, detect problems and manage increasingly complicated computing environments.
AI can make that problem larger.
Datadog reported second-quarter revenue of $1.12 billion, up 36% year over year. It also generated $279 million in free cash flow during the quarter, while the number of customers producing at least $100,000 in annual recurring revenue rose from roughly 3,850 to 4,720.
The company has been adding AI products of its own, but the broader economic argument does not require every Datadog customer to buy an AI-branded feature. More AI workloads can mean more models, agents, APIs, GPUs, cloud services and automated processes that companies need to observe and secure.
Datadog therefore illustrates a potentially important second-order AI trade.
Instead of asking how much infrastructure must be built, investors can ask which companies earn more money because businesses are actually using that infrastructure.
Its 4% gain on Monday was one trading session, not evidence that Wall Street has permanently rotated from chips into software. Datadog shares were almost flat the following day.
But the underlying financial question survives the stock move.
Can AI create recurring software revenue at a pace that begins to rival the market’s obsession with infrastructure spending?
Akamai sits awkwardly between both worlds
Akamai makes the proposed split even messier.
The company is known for content delivery and cybersecurity, but it has also been expanding its cloud infrastructure business. In the second quarter, Akamai generated $1.1 billion in total revenue. Security revenue grew 10% year over year to $604 million, while Cloud Infrastructure Services revenue jumped 39% to $99 million.
Akamai said it had signed multi-year Cloud Infrastructure Services contracts worth more than $2.8 billion year-to-date, including one agreement worth more than $600 million over four years with a US technology company.
In other words, Akamai can benefit from applications, cybersecurity demand and infrastructure spending at the same time.
Its stock performance this week also provides a useful warning against forcing a clean narrative onto noisy market data. Akamai fell 1.1% during Monday’s AI-driven selloff and gained only modestly on Tuesday. Its stronger recent move came earlier in September.
That makes it a poor exhibit for the claim that “application stocks rallied while infrastructure stocks collapsed.”
It makes it a much better exhibit for the actual point.
Wall Street increasingly needs to decide which part of an AI company’s economics it is paying for.
Akamai’s security business has different margins, growth drivers and capital requirements from its cloud infrastructure operation. If investors become more selective about AI exposure, those distinctions should matter more, not less.
Wall Street may be moving from construction to monetization
The first years of the generative AI boom were dominated by a relatively straightforward problem: there was not enough compute.
That scarcity rewarded the companies capable of supplying it. Nvidia became the defining corporate beneficiary, memory demand exploded, networking became a major AI theme and data-center construction accelerated around the world.
The next question is harder.
What is all that compute worth once it has been installed?
The industry does not need to stop building infrastructure for Wall Street to become more demanding about the answer. Spending can continue growing while investors simultaneously demand clearer evidence of returns.
That distinction matters because the numbers involved are becoming enormous. Meta alone expects up to $145 billion of 2026 capex. Across the wider industry, hyperscalers, AI laboratories, cloud providers and newer infrastructure companies are committing extraordinary amounts of capital to the same broad thesis.
For several years, rising capex was itself interpreted as bullish evidence for the AI trade. Every additional billion spent implied more GPUs, more networking, more memory and more capacity.
Eventually, the market has to connect those billions to revenue.
That could come through advertising efficiency at Meta, cloud consumption, coding tools, cybersecurity, observability, enterprise agents, search, commerce or applications that have yet to establish meaningful businesses.
The important change would not be Wall Street deciding that AI infrastructure no longer matters.
It would be investors beginning to distinguish between companies paid to build the AI economy and companies capable of extracting recurring profits from what has already been built.
Those are related businesses. They are not the same financial proposition.
What would confirm that the AI trade is really splitting?
One volatile week cannot answer whether this is a lasting rotation. Earnings can.
For infrastructure suppliers, the obvious numbers remain orders, backlog, data-center revenue, customer concentration and guidance. If Nvidia, Broadcom, Micron and other suppliers continue reporting accelerating demand despite higher rates and the AI safety debate, the infrastructure thesis remains financially intact regardless of short-term stock volatility.
Hyperscalers face a more demanding test. Investors can compare capital expenditure growth against operating income, free cash flow and measurable AI-related revenue. Meta’s second quarter illustrates the tension particularly well: revenue grew 28%, but free cash flow fell to $784 million as capital spending surged.
That does not establish that the investment is uneconomic. It shows why the return on that investment is becoming one of the market’s most important questions.
For software companies, the test is different. Investors should be able to see AI contributing to customer growth, usage, retention, pricing or margins without infrastructure costs consuming the resulting revenue.
Datadog’s growth offers one example worth following. Future results will show whether AI-driven complexity continues translating into durable usage and cash generation rather than merely providing another product-marketing narrative.
A genuine separation in the AI trade would eventually become visible across several earnings cycles: infrastructure spending growth moderating or becoming more selective while application-layer revenue, margins and free cash flow demonstrate that businesses are extracting more value from the compute already deployed.
If chip demand keeps accelerating at the same time, then the story becomes even more interesting. The market would not be rotating out of AI infrastructure at all.
It would simply be expanding its definition of what successful AI economics look like.
That is why this week’s divergence deserves attention without deserving a verdict yet.
For years, “bullish on AI” could function as a surprisingly broad investment thesis.
Wall Street may now be asking the question that comes after the boom begins to mature:
Bullish on which part?
The AI trade: key questions
What is the AI trade?
The AI trade is a broad market term for companies expected to benefit financially from artificial intelligence, including semiconductor manufacturers, data-center suppliers, cloud providers, model developers and software companies.
Why did semiconductor stocks fall on September 14?
Chip stocks sold off sharply after prominent AI executives called for slowing advanced AI development over safety concerns. Investors interpreted a possible slowdown as a potential risk to the extraordinary pace of infrastructure spending that has supported semiconductor demand.
Why could higher Treasury yields hurt AI infrastructure companies?
Large AI infrastructure projects require substantial upfront capital. Higher long-term interest rates can increase financing costs and make future cash flows less valuable relative to returns available from government bonds.
Why is Meta different from a semiconductor company?
Meta spends heavily on AI infrastructure but also owns enormous consumer platforms and an advertising business that can potentially monetize AI directly. It is therefore both a major buyer of AI infrastructure and an application-layer beneficiary.
How can Datadog benefit from AI?
AI applications increase computing complexity, creating additional demand for tools that monitor, analyze and secure software and infrastructure. Datadog also sells its own AI-enabled products.
Is Akamai an AI infrastructure or software company?
It has exposure to both. Akamai operates security, content-delivery and cloud infrastructure businesses, making it an example of why the AI ecosystem cannot always be divided neatly into two categories.
What would prove that Wall Street is splitting the AI trade?
Several quarters of divergent financial and market performance would provide stronger evidence. Investors would need to see differences in capex returns, revenue growth, margins, free cash flow and demand between infrastructure suppliers and companies monetizing AI through software and services.
Is this financial advice?
No. This article is editorial analysis for informational purposes only and does not constitute investment, trading or personalized financial advice.
Sources: Reuters reporting on the September 14-15 AI market selloff and US Treasury yields; Meta Q2 2026 SEC filing; Datadog Q2 2026 results; Akamai Q2 2026 results.